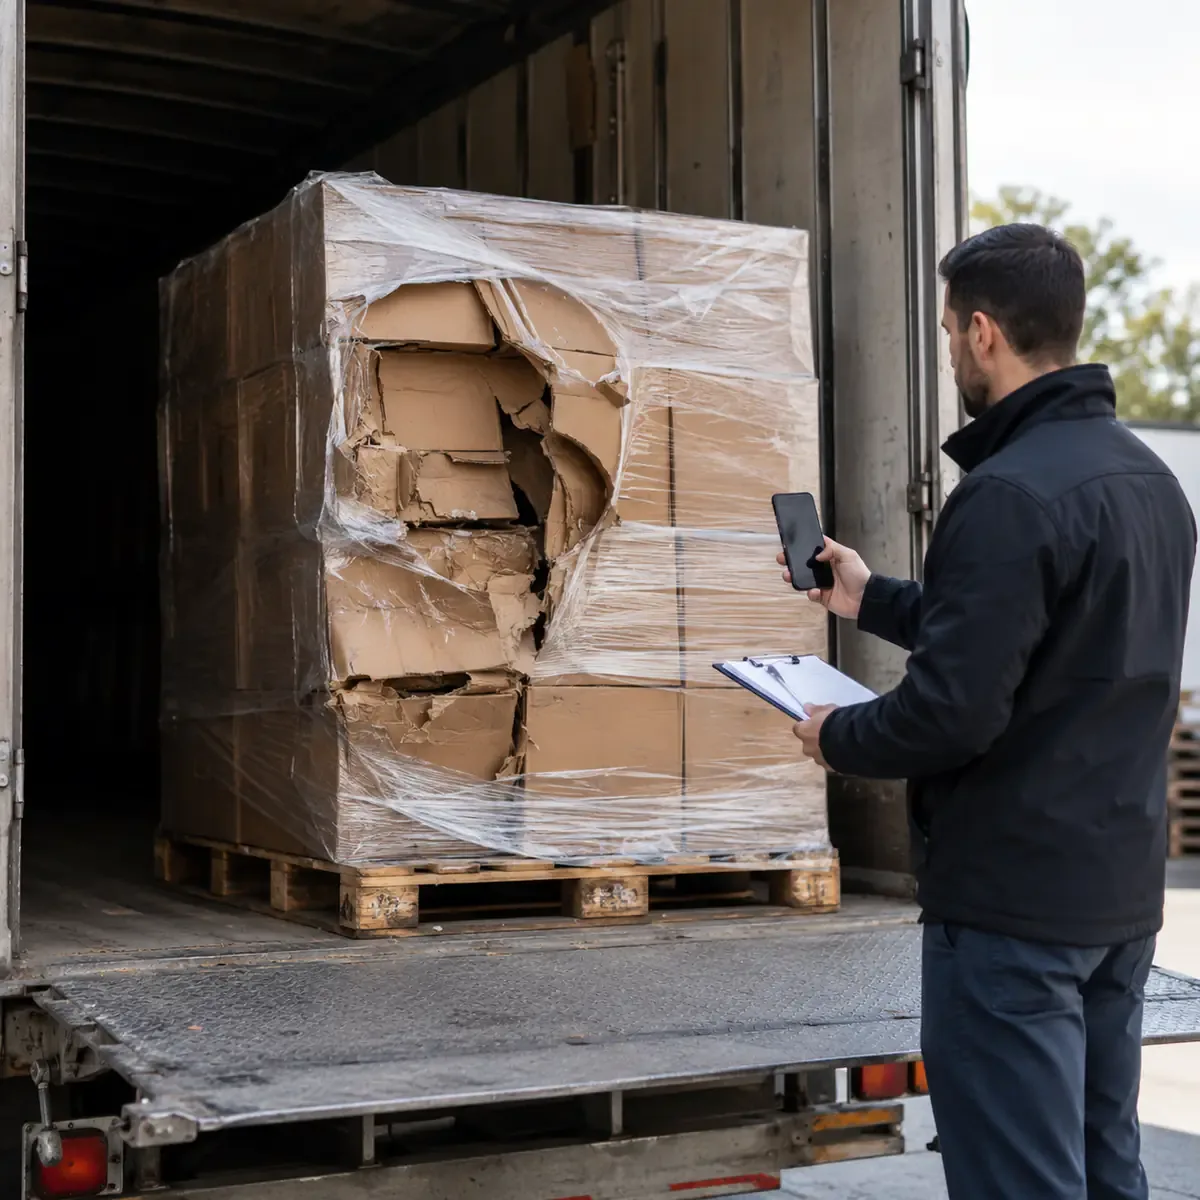
Cargo damage creates two clocks at the same time.
The first starts at the dock:
protect the freight, document what happened and prevent the loss from getting worse.
The second starts when a formal claim arrives:
create the claim file, investigate liability and value, communicate on time and preserve the carrier’s defenses.
A small motor carrier can handle the first clock well and still mishandle the second.
For example, the driver may take excellent photos and obtain a damaged-delivery notation, while the office later:
- treats that notation as the formal claim;
- never assigns a claim number;
- fails to acknowledge a proper claim;
- throws away salvage;
- sends the insurer incomplete documents;
- misses a contractual defense;
- or allows weeks of inconsistent email explanations to become the carrier’s unofficial position.
The objective is not to deny every cargo claim.
It is to make the outcome defensible.
That means separating facts, liability, value, insurance and settlement instead of treating “damaged cargo” as one administrative task.
The first hour: preserve the facts before arguing about liability
When damage is discovered, the driver and dispatcher should avoid beginning with:
“Who is paying for this?”
The first question is:
“What evidence will exist tomorrow that shows the condition of the shipment right now?”
Cargo condition can change quickly.
A wet carton dries.
A shifted pallet gets restacked.
A reefer temperature rises after the doors open.
A broken seal is replaced.
A consignee moves freight away from the dock.
A forklift puncture becomes difficult to reconstruct after unloading.
The carrier should therefore preserve the scene before the evidence disappears.
Capture the condition
Useful evidence can include:
- wide photos showing the trailer and load position;
- close photos of visible damage;
- pallet labels and product identifiers;
- seal number;
- trailer number;
- tractor/unit information;
- cargo securement;
- packaging condition;
- temperature data when relevant;
- reefer set point and download;
- delivery time;
- weather or water intrusion evidence where relevant.
The objective is not to create dramatic photographs.
It is to allow someone who was not present to understand:
- what was shipped;
- what arrived;
- where it was located;
- how it was packaged;
- what damage was visible.
Do not destroy the chain of custody
Cargo claims often become fact disputes.
The carrier should preserve enough information to reconstruct custody:
Pickup
- shipper;
- date/time;
- bill of lading;
- piece count;
- seal;
- driver’s observations.
Transit
- trailer changes;
- stops;
- temperature records;
- accidents;
- securement checks;
- breakdowns.
Delivery
- consignee;
- arrival;
- seal;
- shortage/damage notation;
- rejected freight;
- photos.
When a carrier cannot explain who controlled the freight and when, the claim becomes harder to investigate.
What the driver should write on the delivery record
The driver should be factual.
Better:
“Two cartons on pallet 7 visibly crushed at lower right corner. Consignee photographed before removal.”
Worse:
“Carrier damaged product.”
The first records an observation.
The second can be read as a conclusion about legal responsibility.
Drivers should document:
- visible condition;
- count discrepancy;
- seal issue;
- refusal;
- time;
- people present.
They should avoid making settlement promises or liability admissions from the dock.
Hidden damage is different from visible damage
Some damage is discovered only after:
- packaging is opened;
- pallets are broken down;
- product is inspected;
- a customer uses the item.
The absence of a visible delivery notation can be relevant evidence.
It does not answer every concealed-damage dispute automatically.
The carrier should investigate:
- packaging;
- handling;
- delivery condition;
- timing of discovery;
- who controlled the freight after delivery;
- whether photographs or inspection records exist.
A carrier should not create a blanket rule that every concealed-damage claim is automatically invalid.
The legal and contractual analysis is more specific.
The cargo claim and the insurance claim are two different files
This distinction is essential.
File A — Claim against the motor carrier
The claimant says the carrier owes money because freight was:
- lost;
- damaged;
- short;
- delayed.
This file is governed by the applicable transportation contract, federal law where applicable and the Part 370 claim-processing rules.
File B — Carrier’s insurance notification
The carrier asks whether its motor truck cargo policy responds to the event.
That process is governed by the policy.
The carrier should not wait for the customer claim process to finish before determining whether the insurer requires notice.
The motor truck cargo insurance guide explains why a cargo limit alone does not tell the carrier whether a particular loss is covered.
The insurer does not replace the carrier’s claim process
A common operational mistake is forwarding the customer’s email to the insurer and assuming the carrier has no further role.
The carrier still needs to preserve:
- claimant communications;
- claim date;
- acknowledgment;
- investigation;
- supporting documents;
- settlement or denial;
- status updates.
The insurance adjuster can be central to the response.
The motor carrier remains the contractual/regulatory counterparty unless the applicable arrangement changes that responsibility.
When does a message become a proper cargo claim?
49 CFR § 370.3 gives a useful federal minimum.
A written communication filed with the proper carrier qualifies when it:
- contains enough facts to identify the shipment;
- asserts liability for the loss, damage, injury or delay;
- makes a claim for a specified or determinable amount of money.
All three matter.
| Communication | Likely significance | Carrier response |
|---|---|---|
| “3 cartons damaged” on POD | Important delivery evidence, but not sufficient by itself under § 370.3 | Preserve and investigate the event |
| Photos emailed with no demand | Evidence of alleged damage, not necessarily a complete claim | Preserve; ask for formal claim information if needed |
| Written demand identifying shipment and requesting $4,850 | Can satisfy the minimum filing elements if liability is asserted | Date-stamp and open formal claim file |
| “Claim amount TBD” with no determinable value | May not yet satisfy the specified/determinable amount requirement | Request adequate valuation information |
The carrier should not use technical defects as an excuse to ignore the communication.
If a shipper clearly reports a loss but has not yet supplied a proper claim, acknowledge the issue operationally and request what is needed.
A shortage notation alone is specifically insufficient
Part 370 is unusually clear here.
Standing alone, the following do not satisfy the minimum filing requirements:
- bad order reports;
- appraisal reports;
- shortage/damage notations on freight bills;
- shortage/damage notations on delivery receipts;
- inspection reports.
This matters because carriers sometimes count the nine-month or other contractual claim period from a document that was never actually a formal claim.
The correct approach is to preserve both dates:
- date damage was reported;
- date a proper written claim was received.
The claim deadline is not simply “nine months”
This is one of the most repeated oversimplifications in trucking cargo claims.
49 U.S.C. § 14706—the Carmack Amendment framework—provides that a carrier may not set, by rule or contract, a period shorter than nine months for filing a claim.
That creates a statutory floor.
It does not mean every shipment has one universal federal claim deadline of exactly nine months.
The applicable:
- bill of lading;
- tariff where relevant;
- broker-carrier agreement;
- shipper-carrier contract
should be reviewed.
A contract can provide the applicable claim-filing period as long as it does not violate the federal minimum where Carmack governs.
The lawsuit period is also a minimum
Section 14706 likewise prevents the carrier from providing less than two years for bringing a civil action.
The statute measures that civil-action period from the date the carrier gives written notice that it has disallowed any part of the claim specified in the notice.
That is why a denial letter should be treated as a legal document, not a casual email.
Interstate versus intrastate claims
The Carmack Amendment is central to interstate motor-carrier cargo liability.
Not every freight dispute is identical.
The legal framework can differ when transportation is:
- purely intrastate;
- international;
- multimodal;
- exempt;
- governed by a specialized contract.
A carrier should therefore begin claim analysis by identifying the transportation involved rather than assuming every cargo incident follows the same liability rules.
For a difficult or high-value claim, legal advice can be appropriate.
Open a separate file for every proper claim
Part 370 requires carriers receiving claims to create a separate claim file and assign a successive claim number.
A practical claim file should include:
Identity
- internal claim number;
- claimant;
- carrier;
- driver;
- broker;
- shipper;
- consignee.
Shipment
- PRO/load number;
- BOL;
- pickup;
- delivery;
- commodity;
- piece count;
- weight;
- seal.
Incident
- photos;
- driver statement;
- accident report if applicable;
- temperature data;
- inspection;
- rejection record.
Claim
- formal written demand;
- amount;
- date received;
- acknowledgment;
- supporting invoices;
- correspondence.
Insurance
- insurer claim number;
- notice date;
- adjuster;
- reservations/coverage communications.
Outcome
- liability analysis;
- valuation;
- salvage;
- settlement;
- denial;
- release;
- payment.
That structure allows the carrier to answer the entire claim without searching across dispatch texts and accounting inboxes.
The 30-day acknowledgment clock
Under 49 CFR § 370.5, the carrier generally must acknowledge a proper claim within 30 days after receipt unless it has already paid or declined the claim in writing within that period.
The acknowledgment should also identify additional documentary evidence or information needed to process the claim when the preliminary review reveals a need.
This makes the acknowledgment useful.
A good acknowledgment can state:
- claim number;
- date received;
- shipment;
- claimed amount;
- documents still required;
- claim contact.
It should not prematurely promise payment.
Date-stamp the claim
Part 370 requires the carrier to record the date the claim is received.
That date drives later communication deadlines.
A shared inbox without a controlled received date is a weak claims system.
Investigation should answer liability and value separately
A carrier can believe it is liable and still disagree with the amount.
A carrier can dispute liability while agreeing that the product value documentation is accurate.
Separate the questions.
Liability investigation
Ask:
- Was freight received in apparent good condition?
- What does the BOL say?
- What happened in transit?
- Was the load sealed?
- Who loaded and secured?
- Was packaging sufficient?
- Was damage visible at delivery?
- Was there a delay?
- Was the shipment rejected?
- Did an accident occur?
- Is there evidence of inherent vice or another relevant cause?
Value investigation
Ask:
- What property was actually lost/damaged?
- What quantity?
- What invoice supports value?
- Was product repairable?
- Was product still saleable?
- Is there salvage?
- Are discounts or depreciation relevant to the specific claim?
- Is consequential loss being demanded?
Part 370 expressly allows the carrier to require supporting documents such as the bill of lading, freight-charge evidence and invoice/value documentation when necessary to investigate.
Do not pay from the invoice headline alone
Suppose the claimant submits:
Invoice value: $80,000
Claim: $80,000
That does not automatically establish an $80,000 carrier payment.
The file still needs to answer:
- Was all $80,000 cargo damaged?
- Can part be repaired?
- Was part delivered?
- Is part salvageable?
- Does the contract limit liability?
- Does the claimed amount include items outside recoverable cargo value?
- Is the claimant entitled to make the claim?
Investigation is not bad faith.
It is the process Part 370 requires.
The 120-day decision point
49 CFR § 370.9 establishes the next major carrier deadline.
For a proper written claim, the carrier must generally:
- pay;
- decline;
- or make a firm compromise settlement offer
within 120 days after receipt.
When the claim cannot be resolved by then, the carrier must send written status explaining:
- that the claim remains pending;
- why final disposition is delayed.
Then another written status is required at the end of each succeeding 60-day period while the claim remains unresolved.
| Point in file | Carrier action |
|---|---|
| Proper claim received | Record receipt date, assign claim number, open separate file |
| Within 30 days | Acknowledge unless already paid or declined in writing |
| Promptly | Investigate thoroughly and request necessary support |
| By 120 days | Pay, decline or make firm compromise offer—or send written status/reason for delay |
| Every following 60 days | Send another written status while claim remains pending |
A spreadsheet calendar is enough for a one-truck carrier.
The deadline should not live only in someone’s memory.
Scenario: the consignee rejects an entire pallet
Salvage cannot be treated as trash
Damaged freight can still have economic value.
Part 370 contains specific salvage rules.
When damaged property is not delivered or is rejected/refused, the carrier—after giving notice where practicable to interested parties and unless instructed otherwise—may need to arrange sale or disposition directly or through a competent salvage agent.
The disposition must fairly protect the interests of the parties involved.
The carrier must also maintain records tying salvage to:
- shipment;
- claim;
- lot;
- recovery proceeds.
Do not dispose simply because warehouse space is inconvenient
Premature disposal destroys evidence and can destroy value.
Before salvage or destruction, confirm:
- owner instructions;
- insurer instructions;
- health/safety requirements;
- brand-protection concerns;
- product restrictions;
- inspection needs.
Some damaged commodities genuinely cannot be resold.
That conclusion should be documented.
The claimant has an interest in salvage too
If a claimant seeks the full value of freight but usable value remains, salvage becomes part of the economic calculation.
The carrier should not secretly sell rejected freight and keep the proceeds.
Part 370 requires records of salvage recovery and transmission of proceeds to persons lawfully entitled to receive them.
That makes salvage a claim-file issue, not miscellaneous carrier revenue.
Cargo insurance limits do not determine carrier liability
Suppose:
- alleged cargo loss = $150,000;
- cargo policy limit = $100,000.
It does not follow automatically that:
“The carrier only owes $100,000.”
Insurance coverage and legal liability are different questions.
The policy tells the carrier what the insurer may cover subject to terms, limits, deductibles and exclusions.
The transportation contract and applicable law determine the carrier’s liability to the cargo interest.
The reverse is also true.
A carrier can face a $30,000 claim and discover that the policy excludes the particular commodity or circumstance.
This is why the insurance review should occur before accepting freight—not after damage.
Broker instructions do not replace the carrier’s insurer notice
When a broker sends:
“Please send all cargo claims to our claims department,”
follow the contractual process.
But do not assume that notifying the broker automatically notifies the carrier’s cargo insurer.
The carrier should know its own policy notice requirements.
A late-notice issue is avoidable.
Preserve electronic evidence early
Some useful claim evidence can disappear through ordinary retention cycles.
Examples include:
- ELD position data;
- reefer downloads;
- dash camera footage;
- telematics;
- dispatch messages;
- electronic BOL;
- tracking history.
When an incident is reported, place a preservation hold on relevant electronic evidence.
Do not wait until the formal claim arrives months later.
By then the data may be gone.
Theft claims require a different first response
For theft or suspected cargo crime, immediate priorities can include:
- driver safety;
- law enforcement;
- insurer notification;
- broker/shipper notification;
- GPS/telematics preservation;
- trailer/tractor location;
- seal records.
Do not delay emergency action because Part 370’s formal claim process has not started.
The regulatory claim file comes afterward.
Temperature claims need more than a product-temperature allegation
Reefer cargo can produce complex disputes.
Preserve:
- set point;
- continuous temperature data where available;
- pulp/product temperature observations;
- pre-cool information;
- reefer fuel;
- alarm history;
- door openings;
- loading condition;
- seal;
- transit time.
A customer’s receiver temperature at one moment may be important.
It is not necessarily the entire transit record.
The claim file should reconstruct the temperature story.
Shortage claims should begin with count and seal evidence
For an alleged shortage:
- compare BOL quantity;
- shipper load/count notation;
- seal at pickup;
- seal at delivery;
- intermediate stops;
- delivery count;
- pallet/serial identifiers.
A generic “2 pieces short” email is not enough to understand where the discrepancy occurred.
Damage from loading creates a fact question
Drivers often arrive at sealed or shipper-loaded freight.
The carrier should preserve whether the shipment was:
- driver count;
- shipper load and count;
- sealed;
- accessible for inspection;
- loaded by shipper employees.
These facts can be relevant to liability and defenses.
Do not add “SLC” or other notations after the fact.
The shipping document should reflect what actually happened at pickup.
Settle only after the file explains the number
A settlement should connect to evidence.
The claim file should be able to show:
Claimed
- $18,600
Supported property loss
- $15,000
Less salvage/usable value
- $2,000
Other contractual/legal adjustment
- documented basis
Settlement
- reasoned amount
The exact calculation depends on the claim.
The principle is that settlement should not be an unexplained round number approved because everyone wants the file closed.
A denial should be equally disciplined
A denial should identify the carrier’s position clearly enough that the claimant understands the disposition.
Because the Carmack civil-action period can run from written notice of disallowance, denial language deserves care.
High-value or contested claims should be reviewed appropriately before sending a final legal position.
Avoid emotional or accusatory language.
The file should show:
- facts;
- contract;
- applicable rule;
- evidence;
- conclusion.
Claim payments should close the paperwork too
When settling, document:
- agreed amount;
- claimant;
- payment;
- release when appropriate;
- salvage treatment;
- insurer reimbursement/payment;
- deductible;
- accounting treatment;
- claim closure date.
Do not let dispatch believe a claim is closed because “insurance handled it” while accounting still shows an open deduction.
What to do when a broker deducts the claim from freight payment
A broker may assert contractual rights to:
- offset;
- withhold;
- deduct.
Whether a particular deduction is allowed depends on the contract and facts.
Do not automatically concede the cargo claim simply because money was withheld.
Reconcile:
- broker-carrier agreement;
- rate confirmations;
- claim documents;
- invoices;
- settlement;
- factoring position.
This is especially important when invoices have been assigned to a factor.
The factoring-contract guide explains why offsets and chargebacks can affect the carrier beyond the original load.
A practical internal claim-status system
A small carrier can use six statuses.
| Status | Meaning |
|---|---|
| Incident only | Loss/damage reported, but no proper written claim yet |
| Claim received | Formal claim received and date-stamped |
| Investigating | Liability/value evidence being collected |
| Insurer involved | Insurance claim or coverage review active |
| Settlement/denial pending | Disposition being finalized |
| Closed | Payment, denial or other final disposition documented |
Then add three dates:
- claim received;
- 30-day acknowledgment deadline;
- 120-day disposition/status deadline.
That simple control catches most administrative failures.
Common cargo-claim mistakes
Admitting liability from the dock
Document facts first.
Assuming the POD is the formal claim
It may not satisfy § 370.3.
Waiting for a formal claim before notifying insurance
The policy may require earlier notice.
Throwing away rejected cargo
Salvage and evidence can matter.
Treating the policy limit as the liability limit
Coverage and legal liability are separate.
Ignoring an incomplete claim
Request the missing information and preserve the date/history.
Forgetting the 30/120/60-day communications
A valid claim can become an administrative compliance failure.
Using “nine months” without reading the contract
Carmack establishes a minimum contractual filing period, not an excuse to ignore the bill of lading.
The carrier’s claim file should answer ten questions
- What shipment is involved?
- What exactly was lost, damaged, short or delayed?
- When and where was the problem discovered?
- What contemporaneous evidence exists?
- When did the proper written claim arrive?
- What amount is claimed and how is it supported?
- What does the transportation contract say?
- What did the insurer say about coverage?
- What is the salvage position?
- What disposition and deadlines remain?
When those ten answers are visible, claims management becomes far less chaotic.
Keep the claim moving in sequence
Cargo claims should be managed in sequence:
preserve → notify → separate files → formal claim → investigate → value → salvage → communicate → settle or deny → close
The most important early mistake to avoid is treating every damage report as though the legal answer is already known.
The most important late mistake is allowing the claim to sit without controlled deadlines.
A motor carrier that documents the shipment, preserves evidence, follows Part 370, reads the applicable transportation contract and coordinates insurance separately is in a much stronger position whether the correct outcome is:
- full payment;
- partial settlement;
- denial;
- or a negotiated resolution.