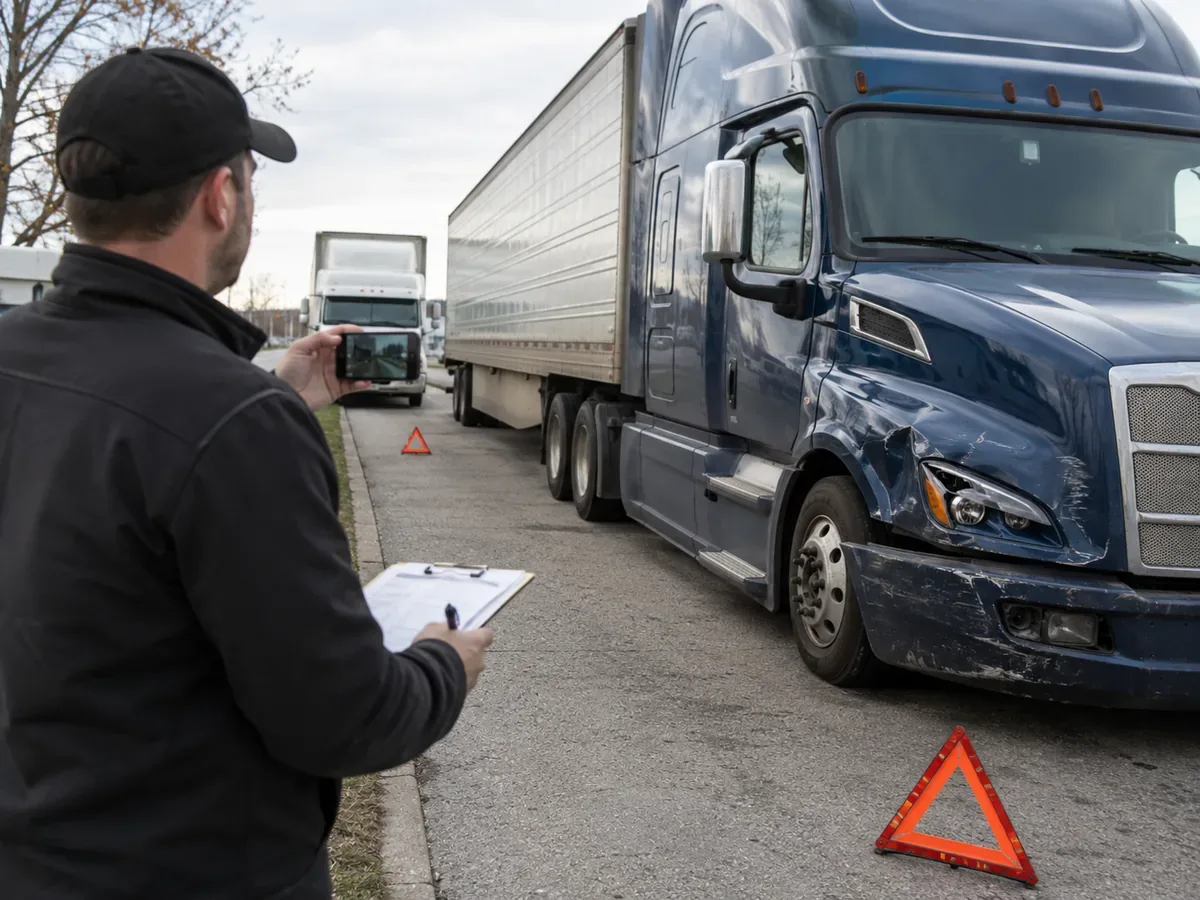
A crash produces paperwork quickly.
The driver may have:
- a police exchange form;
- photographs;
- a towing receipt;
- medical information;
- a citation;
- an insurance claim number;
- a company incident report.
That does not mean every document belongs in the same regulatory category.
For a motor carrier, one of the first compliance questions after the immediate safety response is:
Does this event meet FMCSA’s definition of an accident that belongs on the carrier’s accident register?
That question matters because 49 CFR 390.15 imposes a specific recordkeeping obligation.
The safest process is not to create a spreadsheet called “accidents” and put every scratch, tow and insurance claim into it without distinction.
It is to establish a repeatable gate:
event occurs → determine whether it meets the federal definition → enter qualifying accidents in the register → retain supporting records → calculate the three-year retention date.
First decide whether the event meets the federal definition
FMCSA’s Motor Carrier Safety Planner summarizes a reportable accident under 49 CFR 390.5T as an occurrence involving a commercial motor vehicle in interstate or intrastate commerce in which one of the following occurs:
- a fatality;
- bodily injury requiring immediate medical treatment away from the scene; or
- disabling vehicle damage requiring a vehicle to be transported away from the scene.
That is a more useful compliance test than asking:
“Did we have an insurance claim?”
An insurer may want notification for an event that does not meet the federal accident definition.
A State may impose its own reporting threshold.
A customer contract may require incident reporting.
The company may record minor property damage internally.
Those obligations can all coexist.
They should not be confused with the federal accident-register threshold.
A simple three-question accident gate
A small carrier can make the first classification with three questions.
Did anyone die as a result of the occurrence?
If yes, the event meets the federal accident definition.
Was anyone transported from the scene for immediate medical treatment?
If yes, investigate whether the person actually received treatment of the kind contemplated by FMCSA’s definition.
FMCSA guidance explains that “immediate” means without unreasonable delay: the person is transported from the scene to a medical facility as soon as it is safe and feasible.
The Agency has also distinguished medical treatment from mere observation or diagnostic testing in its interpretive guidance.
The carrier should therefore document what is known rather than assuming that every ambulance trip automatically produces the same regulatory result.
Did disabling damage require a vehicle to be towed away?
This is not simply:
“Was there a tow truck?”
The relevant concept is disabling damage resulting from the accident.
If the commercial vehicle or another motor vehicle cannot safely or normally leave the scene because of accident damage and has to be transported away, that can satisfy the definition.
The reason for the tow matters.
Minor property damage may belong in your internal file without entering the federal register
Consider a tractor that clips a customer’s low fence while backing.
There are:
- photographs;
- a damage claim;
- an insurance notification;
- no injury;
- no fatality;
- no disabling vehicle damage;
- no tow.
The carrier may reasonably create an internal incident file.
The insurer may want the claim.
The customer may want documentation.
But those facts alone do not necessarily make the event an FMCSA-defined accident for the §390.15 register.
This distinction helps prevent the compliance register from becoming an uncontrolled list of every incident the company has ever experienced.
What the accident register must contain
For each qualifying accident, FMCSA requires a minimum set of information.
| Required field | What to record |
|---|---|
| Date | The date the accident occurred |
| Location | The city or town, or nearest city or town, and the State |
| Driver | Name of the driver |
| Injuries | Number of injuries |
| Fatalities | Number of fatalities |
| Hazardous-material release | Whether hazardous materials other than fuel spilled from vehicle fuel tanks were released |
These are the minimum federal fields.
A carrier may choose to add internal fields such as:
- unit number;
- trailer number;
- VIN;
- claim number;
- police-report number;
- insurance carrier;
- internal incident number;
- preventability-review status;
- DataQs status;
- retention-destruction date.
Those can make the file easier to manage.
They do not replace the required fields.
There is no mandatory FMCSA accident-register form
This is a useful point for a small carrier.
FMCSA guidance expressly says there is no specified form.
A carrier may create its own accident register as long as it contains the required §390.15 elements.
That means the register could be maintained as:
- a controlled spreadsheet;
- a database;
- a compliance-software record;
- a paper register;
- another reliable company system.
The format matters less than accuracy, completeness and retrievability.
I would favor a controlled digital register for most small carriers because it makes the three-year retention deadline easier to manage.
But a sophisticated system with incomplete data is worse than a simple spreadsheet that is maintained properly.
A useful register includes a destruction date
The regulation tells the carrier how long to keep the record:
three years after the date of each qualifying accident.
Do not interpret this as:
“We clean the register once every three years.”
Each accident has its own retention clock.
For example:
- accident: January 10, 2026;
- minimum retention point: January 10, 2029.
Another accident occurring in November 2026 has a different three-year period.
Adding an internal field such as:
eligible for routine destruction after
can prevent accidental early deletion.
It can also stop the company from retaining every operational record forever simply because nobody knows when it may be removed.
The register and the accident file are different things
The accident register is the index.
The accident file contains the underlying documentation.
This distinction makes administration much easier.
A register entry might say:
August 12, 2026 — Springfield, Missouri — John Driver — 1 injury — 0 fatalities — no hazmat release.
The corresponding accident file could contain:
- driver incident report;
- photographs;
- insurance correspondence;
- towing documents;
- citation information;
- internal notes;
- governmental reports generated by the carrier;
- claim documentation.
Do not try to put the whole investigation into one spreadsheet cell.
Use the register to identify the accident.
Use the file to preserve the evidence.
Which supporting documents must the carrier retain?
FMCSA has issued guidance specifically on this question.
The Agency explains that §390.15(b)(2) covers information about an accident generated by the motor carrier or driver to fulfill reporting obligations to:
- State entities;
- other governmental entities; or
- the carrier’s insurer.
That is important because it does not mean the carrier has a federal obligation under this provision to search for every document anyone else created.
FMCSA’s guidance states that the rule does not require the carrier to seek out and obtain copies of accident reports prepared by State investigators or insurers.
That does not mean an external police report is useless.
It may be extremely useful operationally, legally or for insurance.
The narrower point is that the federal accident-register requirement should not be described as:
“You must obtain every police report and keep it for three years.”
That overstates the rule.
Example: injury transported from the scene
Suppose a commercial truck is involved in a collision.
The truck remains drivable.
The other vehicle remains drivable.
One person is transported directly from the scene to a medical facility and receives treatment for an injury.
Even without a tow, the event can meet the federal accident definition because of the injury criterion.
The register should therefore not be built around vehicle damage alone.
The compliance person reviewing the incident needs information about:
- injuries;
- treatment;
- transport;
- fatalities;
- vehicle damage.
A driver saying:
“The truck was fine, so it was not reportable”
is not enough.
Example: tow after disabling damage
A tractor is struck in an intersection.
Nobody is injured.
The tractor’s steering is damaged and it cannot be safely driven.
A tow truck transports it from the scene.
That is the kind of fact pattern that can satisfy the disabling-damage element.
The accident file should document why the vehicle was towed.
That distinction can matter later if someone sees only a towing invoice and has to understand what happened.
Example: tow for a reason unrelated to disabling crash damage
Now change the facts.
After a minor parking-lot scrape, the truck is mechanically capable of leaving.
It is later towed because of an unrelated mechanical failure.
The existence of a towing invoice should not automatically be treated as proof that the collision met the disabling-damage threshold.
The carrier needs to understand why the tow occurred.
This is why accident classification should happen close to the event while the facts are still available.
Hazardous-material releases require extra attention
The accident register itself asks whether hazardous materials were released, excluding fuel spilled from the fuel tanks of motor vehicles involved in the accident.
That field should not be treated as a generic yes/no checkbox with no follow-up.
A qualifying hazardous-material incident can trigger separate reporting obligations under the hazardous-material regulations.
FMCSA’s Safety Planner points carriers to 49 CFR 171.15 and 171.16 for hazardous-material incident reporting.
A carrier transporting regulated hazardous materials should therefore have a separate escalation path rather than assuming the accident register satisfies every reporting obligation.
Do not confuse the accident register with crash preventability
A crash can belong on the accident register even when the carrier believes its driver could not have prevented it.
These are different questions.
The accident register asks:
Did this event meet the regulatory accident definition?
Crash preventability asks a different safety-data question.
FMCSA’s Crash Preventability Determination Program can allow eligible crashes to be reviewed through DataQs.
Our DataQs guide explains that process separately.
Do not remove an accident from the internal regulatory workflow merely because:
- the other driver received the citation;
- police said the truck driver was not at fault;
- insurance denied liability;
- the carrier plans to seek a preventability determination.
Accident recordkeeping and preventability review serve different purposes.
Do not rely on the insurance department to maintain the DOT register
Insurance personnel may have the best accident documentation in the company.
That does not automatically mean they maintain the §390.15 register.
Small carriers commonly create an accidental gap between:
claim management
and
DOT compliance.
A useful process defines ownership.
For example:
Driver
- reports the event immediately;
- preserves photographs and documents.
Operations or safety
- determines whether the event meets the federal definition;
- creates the register entry;
- opens the accident file.
Insurance contact
- handles the claim and preserves insurer communications.
Compliance owner
- verifies required fields;
- tracks the three-year retention date;
- responds to audits or investigations.
One person may perform all four roles in a one-truck company.
The roles still need to happen.
The register should reconcile with the carrier’s other records
An auditor should not discover an obvious accident in one company system that has no corresponding compliance review.
Useful reconciliation sources include:
- insurance claims;
- driver incident reports;
- towing invoices;
- internal safety reports;
- crash information visible in FMCSA systems.
The objective is not to force every incident onto the federal register.
The objective is to make sure every potentially qualifying incident was evaluated.
A simple quarterly review can catch:
claim exists → accident classification missing.
That is a much better control than waiting for an audit.
What I would keep in a small carrier’s accident folder
For each qualifying event, I would create one folder named consistently, for example:
2026-08-12_DriverName_Unit123_Springfield-MO
Inside it:
- the company’s incident report;
- driver statement;
- photographs;
- register-entry reference;
- towing information;
- injury information available to the carrier;
- government-reporting documents generated by the carrier or driver;
- insurer-reporting documents;
- citations and dispositions where relevant;
- DataQs or preventability-review records where applicable.
That is an operational recommendation, not a claim that every item is federally mandatory under §390.15.
The benefit is retrieval.
Three years later, the company should not have to reconstruct the accident from five email inboxes.
A five-minute closeout check
Before treating an accident file as complete, verify:
Classification
Does the event meet the FMCSA accident definition?
Register
If yes, has the required register entry been created?
Required fields
Are date, location, driver, injuries, fatalities and hazardous-material release documented?
Supporting records
Are the carrier/driver-generated reports stored?
Retention
Is the three-year retention date calculated?
This is enough structure for a one-truck carrier.
A larger fleet may automate the process.
The compliance logic remains the same.
The goal is a register you can explain
The best accident register is not the one with the most columns.
It is the one where every entry can answer three questions:
Why is this event on the register?
Where is the supporting file?
When can the record be removed under the retention rule?
If the carrier cannot answer those questions, the problem is not spreadsheet design.
It is control of the accident-recordkeeping process.
Keep the register narrow.
Keep the supporting file complete.
And make the classification decision from the federal definition rather than from memory, insurance terminology or assumptions about fault.